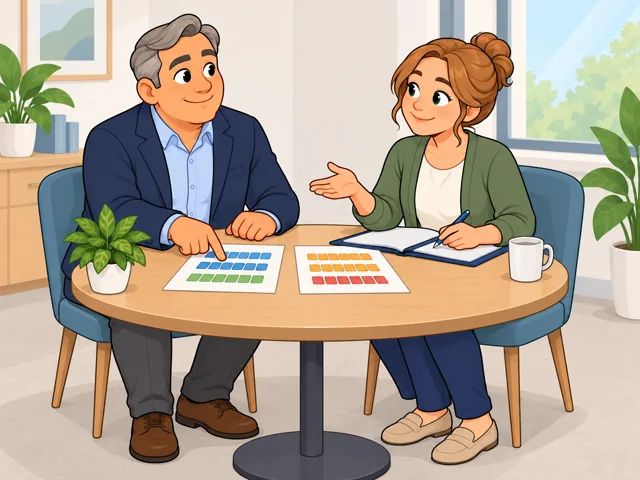
Explain loan choices to an applicant
Ask what the applicant wants to borrow, then explain each loan type on offer and its repayment terms.
Career profile
Loan officers guide people and businesses through applications, then judge whether each borrower can repay.
Between explaining a repayment schedule to one client and catching a missing financial record for the next, the work mixes conversation, careful judgment and sales.
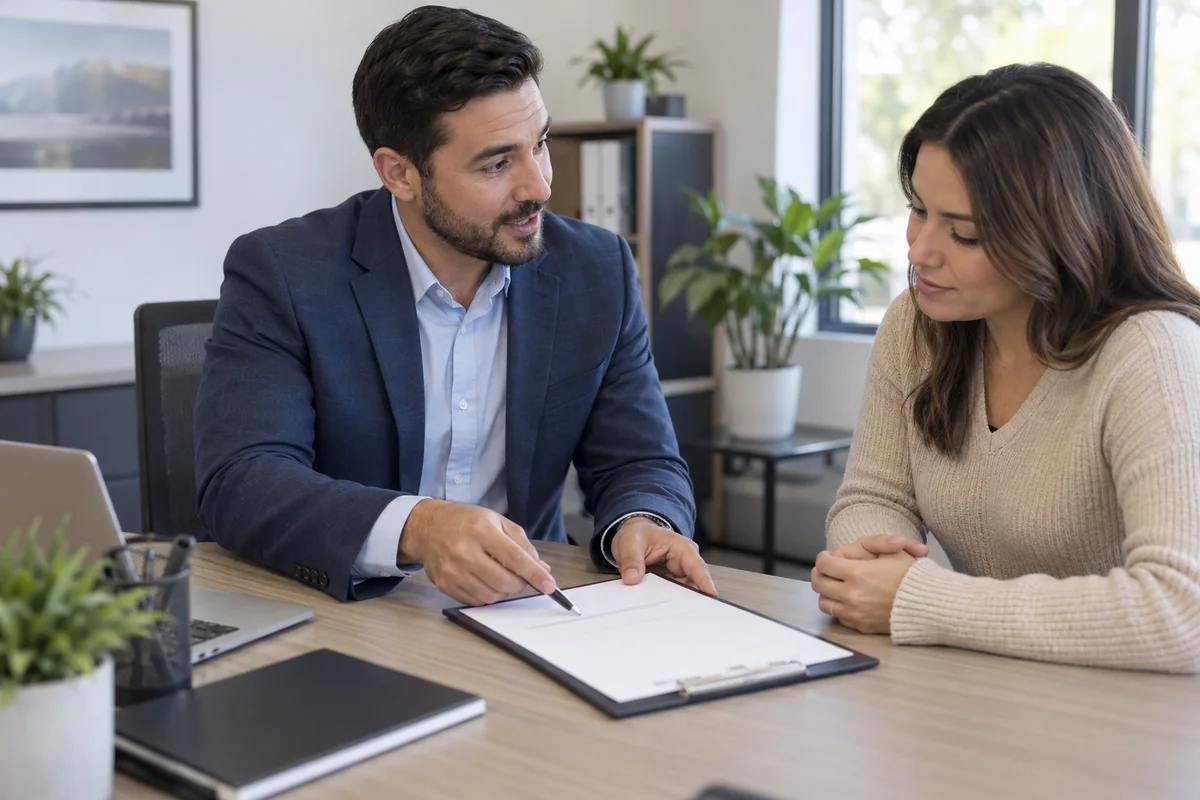
Ask what the applicant wants to borrow, then explain each loan type on offer and its repayment terms.
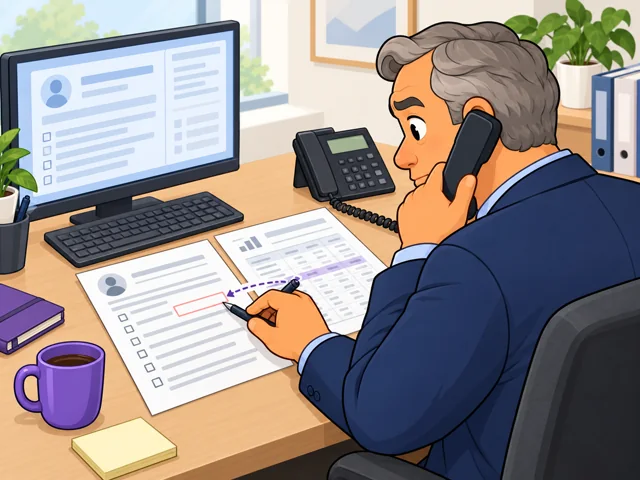
Check the application against the person's money records, and call to ask about figures that do not match.
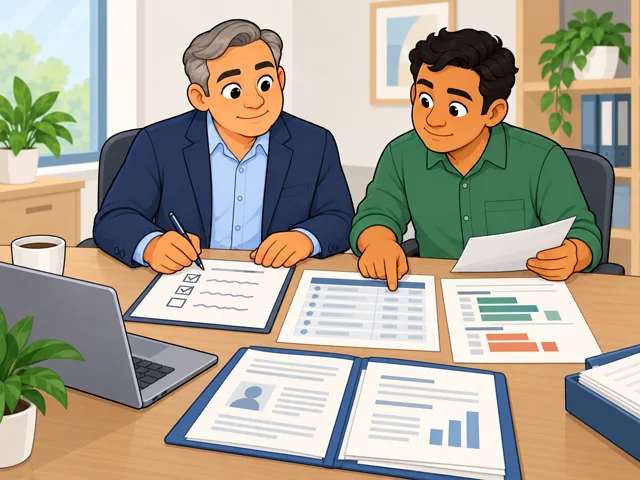
Read the applicant's credit history and finances to judge whether they can repay, then write your approval recommendation.
In jobs with sales duties, you contact likely clients and build ties with referral sources.
United States
United States · May 2025
United States · 2025–2035
Quick orientation
Related work experience can sometimes substitute; employers also provide training.
National median, equivalent to $36.87/hour.
About 17,100 openings annually, mostly to replace workers leaving the occupation.
Software can assess financial information and recommend a loan decision. Some simple consumer loans already have fully automated underwriting.
You explain options, resolve questions, and review information that needs personal attention.
How much application review moves to software will vary with loan complexity and the lender’s methods.
Pay in context
Check how much of an offer is fixed salary and how much depends on loans you bring in.
The median was $76,690 a year, or $36.87 an hour. The 10th and 90th percentile annual wages were $39,430 and $153,180. These describe the workforce, not starting and senior salaries.
Annual medians were $106,000 at automobile dealers, $79,570 in management of companies and enterprises, and $76,070 in credit intermediation and related activities, which includes banks and mortgage companies.
Some employers pay a salary; others combine base pay with commissions. Bonuses may depend on loan volume or performance.
Employment is projected to grow 1% during 2025–35, with about 17,100 openings per year, mostly from replacement needs.
Employers set hiring requirements and loan-approval limits. Residential mortgage work also has the licensing or registration steps below.
After entry
This starts where the entry routes leave off: early work, growing capability, and advancement or specialization. This path also has a credential or licensing boundary; see the requirements and limits.
Learn the lender’s products and procedures through employer training.
Build skill at resolving application questions with applicants and underwriters.
Move toward underwriting specialization or supervising loan staff.
Usually office-based. At some smaller institutions, officers perform underwriting themselves.
Referral relationships with real-estate firms matter. You may meet borrowers away from the office.
Business visits can be part of the week. Large loans may involve coordinating several banks.
Try it
Invent a small-business loan request with a loan amount, monthly sales, expenses, and existing debts. Write three questions you would ask before recommending approval, then explain why each answer matters. Notice whether you enjoy both checking the numbers and explaining your reasoning.
Stay safe: Use fictional information; this exercise cannot determine whether someone qualifies for a real loan.