Sort out where money should go
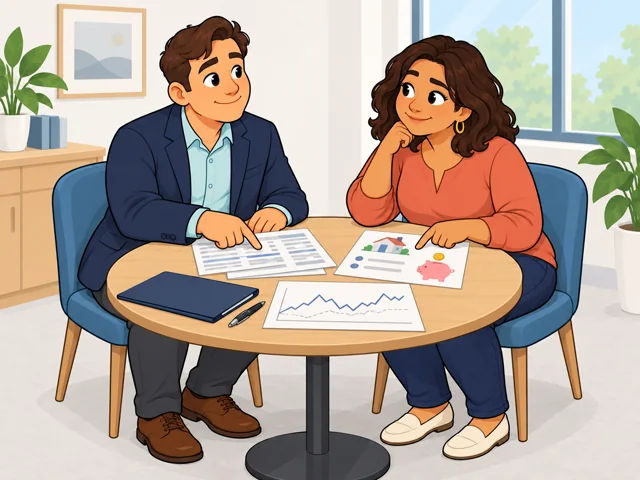
Go over bank statements and debts with a client and ask their goals and comfort with investing risk.
Career profile
Personal financial advisors help people turn their income, savings and goals into a money plan.
Connect a person's numbers to the choices they make, then explain how the plan you recommend would change the way they live.
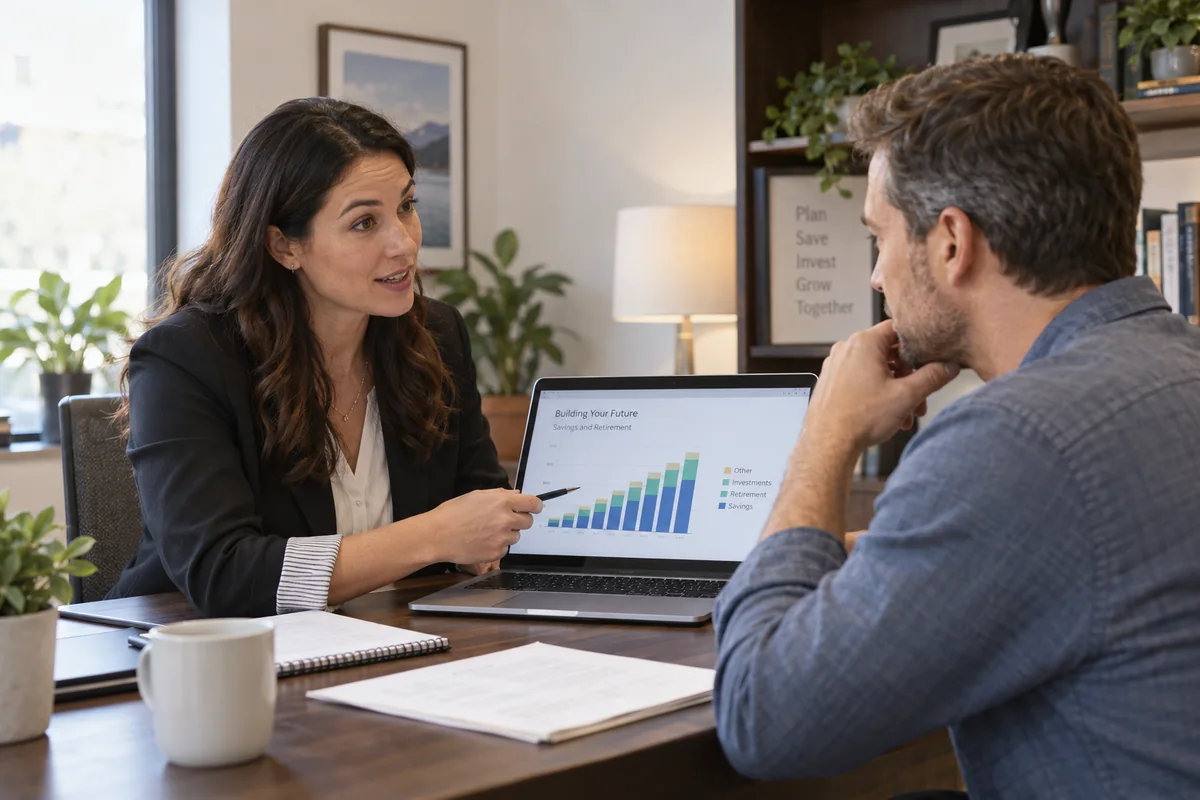
Go over bank statements and debts with a client and ask their goals and comfort with investing risk.
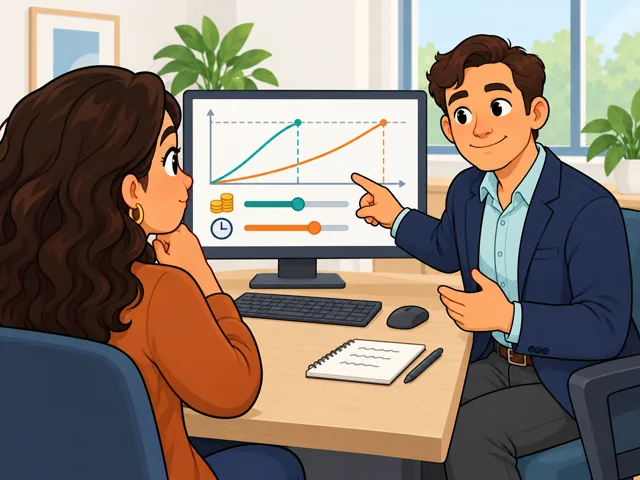
In a spreadsheet or planning tool, test saving more against saving longer, and explain what your pick assumes.
Check a client's account statements and adjust the saving or investing plan to match their new goals.
Explain what you offer, ask what help the person wants, and try to build a lasting working relationship.
United States
United States · May 2025
United States · 2025–2035
Quick orientation
Expect substantial learning on the job after college.
Annual employee wage; equivalent to $50.51 an hour.
About 17,100 openings a year, including replacement needs.
Automated investment services, often called robo-advisers, can build and manage portfolios from questionnaire answers. Some combine automation with access to a person.
You can ask follow-up questions when an answer leaves out something important, such as debt or another savings account, and explain how that changes the recommendation.
How much routine advice clients will hand over to artificial intelligence remains uncertain; the balance between automated service and personal conversations may shift.
Pay in context
Pay varies widely, so read beyond the median.
The median was $105,070 a year, equivalent to $50.51 an hour. The 10th and 90th percentiles were $50,190 and $357,020. These describe the full personal financial advisor occupation, not starting and senior salaries.
Annual medians were $120,870 in securities, commodity contracts, and other financial investment activities, and $84,500 in insurance carriers and related activities.
These wages include commissions, incentive pay, and production bonuses, but exclude nonproduction bonuses and self-employed earnings. They are not a guaranteed base salary.
Employment is projected to grow 1.4% over 2025–2035, with about 17,100 openings annually. Openings include workers leaving the occupation; they are not all newly created jobs.
Education and employer training often connect. Required licenses and registrations depend on your activities, products, and jurisdiction.
After entry
This starts where the entry routes leave off: early work, growing capability, and advancement or specialization.
Learn to organize appointments, prioritize client work, and run the office with help from an experienced advisor.
Build from individual planning conversations toward comprehensive plans and ongoing client relationships.
With strong sales and leadership experience, pursue branch management: coach advisors, help hire staff, and oversee office goals.
In some large branch teams, you work with existing clients, referrals, and walk-ins. Planning colleagues and branch leaders provide support, while a busy appointment flow keeps you moving.
In employer retirement-plan consulting, you travel to meet employees where they work. Conversations focus on plan participation and moving retirement savings, with some visits based in an on-site office.
Try it
Invent a client who wants to save $6,000 in two years. Compare saving $250 monthly with extending the deadline to three years, ignoring interest. Write two questions you would ask before recommending either plan. Notice whether you enjoy both the calculation and the conversation.
Stay safe: Use fictional numbers; no account access or real investment is needed.